Introduction
India’s banking industry has changed significantly over the last few years. Earlier, people had to visit bank branches for almost every banking activity, such as opening an account, transferring money, checking balances, applying for loans, and updating personal details. Today, most of these services are available through mobile applications and internet banking.
The growth of smartphones, affordable internet, Unified Payments Interface (UPI), and digital payment services has made banking easier and faster. Customers can now open savings accounts, transfer money, pay bills, invest, and manage their finances without visiting a physical branch.
This change has also encouraged the growth of digital banking platforms and neobanks. These platforms focus on providing a simple banking experience through mobile applications, online account opening, automated financial management, and instant transactions.
India’s digital banking ecosystem includes traditional banks with advanced mobile applications, small finance banks, payments banks, and fintech companies working with licensed banking partners. It is important to understand that most Indian neobanks are not independent banks. They operate through partnerships with RBI-regulated banks that provide the actual banking services.
In this article, we explore the top 10 digital banks and digital banking platforms in India, their major features, services, strengths, and financial performance wherever reliable public figures are available. The list is based on their digital banking facilities, market presence, customer experience, and contribution to India’s digital financial ecosystem. It is not a strict ranking based on revenue or net profit.
Top 10 Digital Banks in India at a Glance
| Digital Bank / Platform | Main Strength | Banking Partner / Parent Bank |
| Kotak 811 | Digital savings accounts | Kotak Mahindra Bank |
| YONO SBI | Complete digital banking ecosystem | State Bank of India |
| ICICI iMobile Pay | Digital payments and banking | ICICI Bank |
| HDFC Bank | Advanced mobile and internet banking | HDFC Bank |
| Axis Bank | Digital banking and financial services | Axis Bank |
| AU 0101 | Digital banking for retail customers | AU Small Finance Bank |
| IDFC FIRST Bank | Digital savings and banking services | IDFC FIRST Bank |
| Airtel Payments Bank | Payments and everyday transactions | Airtel Payments Bank |
| Jupiter Money | Personal finance management and digital banking | Partner banks |
| Niyo | Digital banking and international travel solutions | Partner banks |
Kotak 811
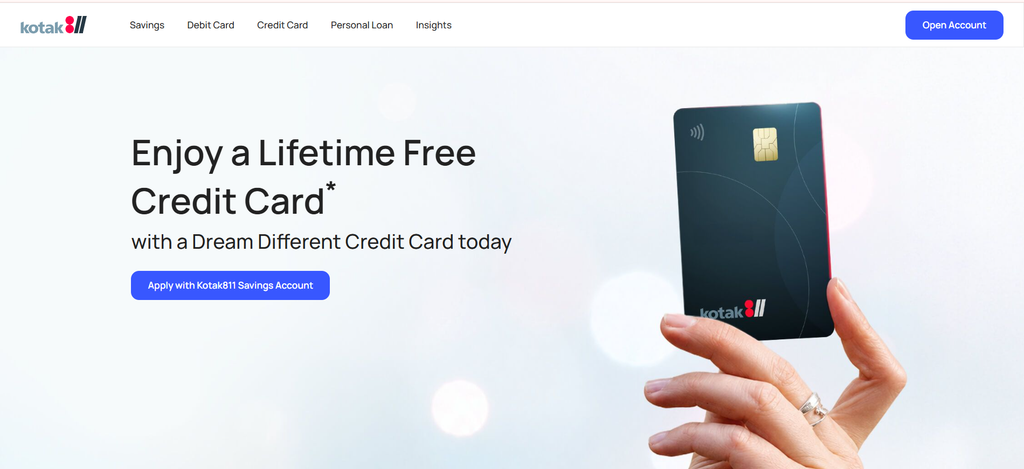
Image Courtesy: Kotak 811(Official Website)
Kotak 811 is one of the well-known digital banking products in India. It is offered by Kotak Mahindra Bank and was introduced to make savings account opening easier through digital technology.
The platform allows customers to open a savings account online without visiting a bank branch. Users can complete the required verification process through their smartphones and manage their accounts through Kotak’s mobile banking application.
Kotak 811 is particularly popular among young professionals, students, and people who prefer managing their money online.
One of its major advantages is convenience. Customers can perform regular banking activities without visiting a physical branch. Kotak 811 also provides different account variants. Their features, transaction limits, and charges may vary depending on the account type and KYC status.
Financial Performance
Kotak 811 operates under Kotak Mahindra Bank, so its financial performance is included in the parent bank’s results. For FY2025-26, Kotak Mahindra Bank reported a net profit of approximately ₹14,008 crore, according to reported annual financial figures. The bank’s financial strength supports its digital banking operations, technology investments, and customer services.
YONO SBI
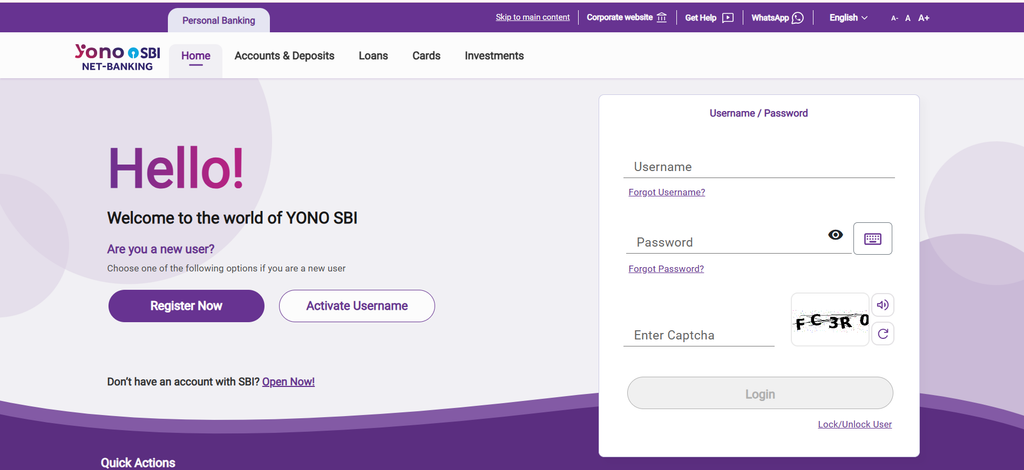
Image Courtesy: YONO SBI (Official Website)
YONO SBI, which stands for You Only Need One, is the digital banking platform of the State Bank of India (SBI). It is designed to provide banking, financial, and selected lifestyle services through a single mobile application. SBI introduced YONO to make banking more convenient for its large customer base.
Through YONO, customers can manage their savings accounts, transfer money, pay bills, apply for loans, and access different financial products.
The platform is especially useful because SBI has a large customer base across urban and rural India. One of YONO’s biggest advantages is that it brings several banking and lifestyle services together in one place.
Customers can also access different SBI services without visiting a branch for routine transactions.
Financial Performance
YONO SBI is not a separate banking company. It is a digital platform operated by the State Bank of India. For FY2025-26, SBI reported a net profit of approximately ₹80,032 crore. This makes it one of India’s largest and most profitable banking institutions.
Its financial strength, extensive customer network, and investments in technology make it an important participant in India’s digital banking growth.
ICICI iMobile Pay
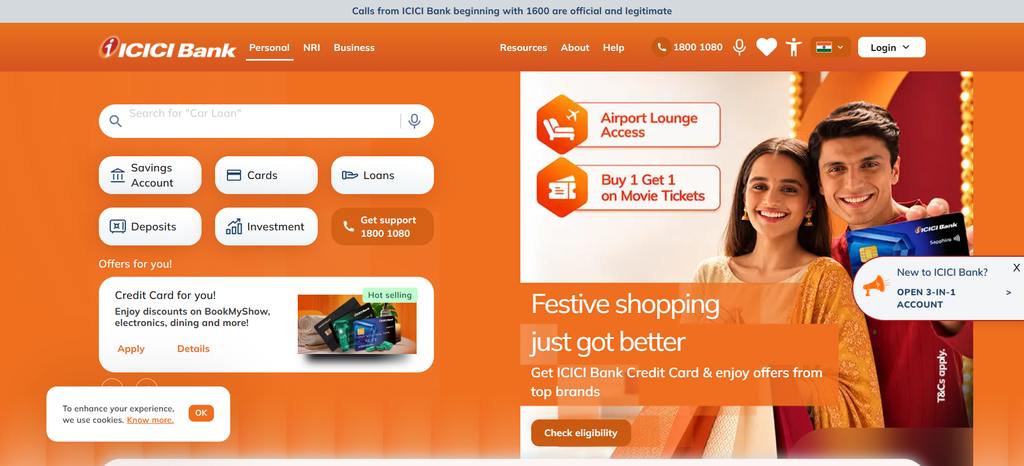
Image Courtesy: ICICI iMobile Pay (Official Website)
ICICI iMobile Pay is the mobile banking application of ICICI Bank. It provides customers with access to banking and payment services through their smartphones.
The application is designed to make everyday financial activities simple. Customers can transfer money, check account balances, pay bills, manage cards, and access different financial products.
One of its important features is that it also supports certain banking and payment services for customers who do not hold an ICICI Bank account. This makes iMobile Pay more than just a traditional mobile banking application.
Key Features
- Savings account management.
- UPI payments and money transfers.
- Credit card and debit card management.
- Online bill payments.
- Fixed deposit and recurring deposit services.
- Personal loan and other financial product access.
- Account statements and transaction tracking.
- Digital payment facilities.
ICICI Bank has continuously invested in digital banking technology to improve customer convenience and provide faster financial services. Its mobile application is particularly useful for customers who prefer handling most banking activities online.
Financial Performance
ICICI iMobile Pay is part of ICICI Bank, and its financial performance is included in the bank’s overall results. For FY2025-26, ICICI Bank reported a standalone profit after tax of ₹50,147 crore, representing growth of approximately 6.2% compared with the previous financial year.
The bank also reported total deposits of approximately ₹17.95 lakh crore as of March 31, 2026. These figures highlight the scale of ICICI Bank’s operations and its ability to support large digital banking services.
HDFC Bank
Image Courtesy: HDFC Bank (Official Website)
HDFC Bank is one of India’s leading private sector banks and has developed a strong digital banking ecosystem. The bank offers mobile banking, internet banking, digital account services, online payments, and financial products through its digital platforms.
Customers can use the HDFC Bank mobile banking application to manage their accounts, transfer money, pay bills, and access different banking facilities. HDFC Bank has also focused on improving digital customer experiences through technology, automation, and online service delivery.
The bank provides a combination of digital services and physical banking facilities. This allows customers to use mobile banking for everyday activities while accessing branches when they need additional support.
Financial Performance
For FY2025-26, HDFC Bank reported a standalone profit after tax of approximately ₹74,671 crore. Its net revenue for the same financial year was approximately ₹1.91 lakh crore.
The bank’s large customer base, financial resources, and technology investments make it one of the important players in India’s digital banking market. HDFC Bank’s digital ecosystem is particularly useful for customers looking for a combination of traditional banking products and modern online services.
Axis Bank
Image Courtesy: Axis Bank (Official Website)
Axis Bank is another major private sector bank in India with a growing digital banking presence. The bank provides several digital services through its mobile banking application and internet banking platform. Customers can use these services for everyday financial activities without visiting branches.
Axis Bank has also introduced digital account opening and online financial product applications to make banking more accessible. Its digital ecosystem supports individuals, salaried professionals, business owners, and corporate customers.
The bank’s digital services help customers manage their finances from almost anywhere. Axis Bank is also investing in technology to improve payment security, customer experience, and digital transaction processing.
According to its FY2025-26 annual report, Axis Bank reported a standalone net profit of approximately ₹24,457 crore. Its operating revenue for the same financial year was approximately ₹82,179 crore. The bank’s financial performance and expanding digital services make it an important participant in India’s banking technology ecosystem.
AU 0101
Image Courtesy: AU 0101 (Official Website)
AU 0101 is the digital banking application of AU Small Finance Bank. The platform provides a range of banking and financial services through a single mobile application. It is designed to make banking convenient for customers who prefer digital transactions.
AU Small Finance Bank has been expanding its digital services while maintaining its presence in physical banking markets. Its mobile application offers more than basic banking facilities and includes payments, card management, investments, and selected lifestyle services.
Key Features
- Digital savings account services.
- UPI payments and fund transfers.
- Account balance and statement checking.
- Debit and credit card management.
- Bill payments and automatic payments.
- Mutual fund-related services.
- Online loan-related services.
- Travel bookings and other lifestyle facilities.
One of the major advantages of AU 0101 is that customers can access several financial services through one application. The application also supports biometric authentication and additional security features to protect customer accounts.
Financial Performance
AU 0101 operates under AU Small Finance Bank, so its earnings are included in the parent bank’s financial statements. For FY2025-26, AU Small Finance Bank reported a profit after tax of approximately ₹832 crore, according to its financial results announcement.
The bank has also continued expanding its customer base and digital banking capabilities. Its focus on technology and financial inclusion makes it an important name in India’s digital banking ecosystem.
IDFC FIRST Bank
Image Courtesy: IDFC FIRST Bank (Official Website)
IDFC FIRST Bank has developed a strong digital banking ecosystem for individual and business customers. The bank provides several services through mobile banking and internet banking platforms. These services allow customers to manage their savings accounts, make payments, transfer money, and access loans.
It has also focused on providing convenient digital account opening facilities and improving the overall customer experience. IDFC FIRST Bank is particularly relevant for customers looking for modern banking services combined with traditional financial products.
Financial Performance
IDFC FIRST Bank reports its financial performance through its regular banking operations. For FY2025-26, the bank’s reported net profit was approximately ₹1,611 crore. Its digital banking services are part of a larger strategy to improve customer relationships, expand its deposit base, and provide technology-driven financial products.
Airtel Payments Bank
Image Courtesy: Airtel Payments Bank (Official Website)
Airtel Payments Bank is one of India’s important digital-first banking institutions. It was launched by Bharti Airtel and operates under the Reserve Bank of India’s Payments Bank framework.
Unlike traditional commercial banks, payments banks have certain restrictions. They can accept eligible deposits and provide payment services but cannot independently provide regular lending services like universal banks.
Airtel Payments Bank focuses on digital payments, savings accounts, money transfers, and everyday financial transactions. Its connection with Airtel’s telecommunications network gives it access to a large customer base.
One of its important advantages is its combination of digital banking and physical banking access through retail banking points. This can be useful for customers who want to use digital payment facilities but also need assistance with basic banking activities.
Financial Performance
Airtel Payments Bank is part of the Bharti Airtel group, but its financial performance should not be confused with the consolidated financial results of the entire telecom company.
Bharti Airtel reported substantial revenue and profit in FY2025-26. However, these consolidated figures include multiple businesses, such as telecom services, digital services, and infrastructure.
Therefore, the parent company’s total net profit should not be treated as the standalone net income of Airtel Payments Bank.
Jupiter Money
Image Courtesy: Jupiter Money (Official Website)
Jupiter Money is a fintech platform that focuses on making personal finance management and banking more convenient.
Unlike traditional banks, Jupiter operates through partnerships with regulated banking institutions. The banking partner provides the underlying banking services, while Jupiter focuses on the digital experience.
The platform is designed mainly for people who prefer managing their finances through mobile applications. Jupiter provides features that help customers track their spending, manage savings, and understand their financial activities.
Financial Performance
Jupiter is a privately held fintech company and does not have a publicly listed standalone banking profit comparable to major commercial banks. Its financial performance is also different from that of its banking partners.
The company operates in India’s growing fintech market, where customer experience, technology, partnerships, and product innovation play important roles. Jupiter is an example of how fintech companies are changing the way people interact with banking services.
Niyo
Image Courtesy: Niyo (Official Website)
Niyo is another well-known fintech platform in India’s digital banking ecosystem. It focuses on providing digital banking experiences, particularly for salaried professionals, travellers, and people who frequently make international transactions.
The platform has worked with regulated banking partners to provide different banking and card-related services. Its offerings have included salary accounts, savings-related facilities, travel cards, and international payment solutions.
Niyo is particularly recognised for its focus on making international spending more convenient for Indian customers.
People travelling abroad often face foreign exchange charges and difficulties managing international payments. Niyo’s travel-focused products aim to make these activities more convenient.
Financial Performance
Niyo is a privately held fintech company. It does not publish a comparable standalone banking net profit like listed commercial banks.
Its business performance should also be separated from the financial results of its banking partners. The company represents the growing role of fintech platforms in improving access to digital financial services.
Revenue and Net Profit Comparison of Digital Banks in India
Financial performance is an important factor when comparing banking institutions. It helps readers understand their business scale, profitability, and financial strength.
However, comparing digital banking platforms with traditional banks requires some care. Most digital banking applications are not separate banking companies. For example, Kotak 811 operates under Kotak Mahindra Bank, while YONO SBI is part of the State Bank of India.
Similarly, fintech platforms such as Jupiter and Niyo work with regulated banking partners.
The following table presents available financial information for selected banking institutions and explains where separate financial figures are not available.
| Bank / Platform | Net Profit / PAT | Financial Year |
| Kotak 811 (Kotak Mahindra Bank) | ₹14,008 crore | FY2025-26 |
| YONO SBI (State Bank of India) | ₹80,032 crore | FY2025-26 |
| ICICI iMobile Pay (ICICI Bank) | ₹50,147 crore | FY2025-26 |
| HDFC Bank | ₹74,671 crore | FY2025-26 |
| Axis Bank | ₹24,457 crore | FY2025-26 |
| AU 0101 (AU Small Finance Bank) | ₹832 crore | FY2025-26 |
| IDFC FIRST Bank | ₹1,611 crore | FY2025-26 |
| Airtel Payments Bank | Separate standalone figure not verified here | Latest filing required |
| Jupiter Money | Not publicly available | Private company |
| Niyo | Not publicly available | Private company |
Important: The figures above refer to the parent banks’ reported profit after tax, not the earnings generated by their individual mobile applications. Figures are rounded. They should not be used as a direct comparison of digital banking revenue or profitability.
Conclusion
Digital banking is becoming an important part of India’s financial ecosystem. The increasing use of smartphones, UPI payments, internet services, and fintech applications has changed how people access and manage their money.
The ten digital banking institutions and platforms discussed in this article offer different services and advantages.
Kotak 811 focuses on convenient digital savings accounts, while YONO SBI provides a wide range of banking and lifestyle services. ICICI iMobile Pay, HDFC Bank, and Axis Bank offer advanced digital banking facilities through their established banking networks.
AU 0101 and IDFC FIRST Bank provide modern banking experiences, while Airtel Payments Bank focuses on digital payments and everyday financial transactions. Jupiter Money and Niyo represent the growing role of fintech companies in making banking more convenient and customer-friendly.
However, there is no single best digital bank for everyone. The right choice depends on individual requirements, account charges, banking facilities, customer support, security, and the services offered by the underlying bank.
As India’s digital economy continues to expand, digital banking platforms are expected to play an even bigger role in making financial services accessible, convenient, and efficient for millions of people.
Frequently Asked Questions (FAQs) :
What is a digital bank?
A digital bank provides banking services through mobile applications and online platforms.
Which is the best digital bank in India?
Kotak 811, YONO SBI, and ICICI iMobile Pay are among the popular digital banking platforms in India.
Is digital banking safe in India?
Yes, digital banking is generally safe when customers use regulated banks and follow proper security practices.
Can I open a bank account online in India?
Yes, many Indian banks allow customers to open savings accounts online using digital KYC.
Which digital bank offers zero-balance accounts?
Kotak 811 offers zero-balance savings account options, subject to account terms and conditions.
Is YONO SBI a digital bank?
YONO SBI is a digital banking platform operated by the State Bank of India.
What is the difference between a digital bank and a traditional bank?
Digital banks focus on online services, while traditional banks generally offer both physical branches and digital banking facilities.
Is Jupiter Money a bank?
No, Jupiter is a fintech platform that provides banking services through regulated banking partners.
What is Airtel Payments Bank?
Airtel Payments Bank is an RBI-regulated payments bank that offers digital savings and payment services.
Can I transfer money through digital banking applications?
Yes, customers can transfer money using UPI, NEFT, IMPS, and other supported payment methods.
Do digital banks provide debit cards?
Yes, many digital banking platforms offer virtual or physical debit cards through their banking partners.
Can I get a loan through digital banking?
Yes, eligible customers can apply for personal loans and other credit products through participating banks.
Which digital banking platform is best for international travellers?
Niyo is a popular fintech platform offering travel-focused banking and international payment solutions.
Do digital banks charge account maintenance fees?
Some digital accounts are free, while others may have minimum balance requirements and maintenance charges.
What is the future of digital banking in India?
Digital banking is expected to grow with increasing smartphone usage, UPI adoption, fintech innovation, and online financial services.