Introduction
Non-Banking Financial Companies (NBFCs) play an important role in India’s financial system. They provide loans, financing options, and other financial services to individuals, small businesses, farmers, and large companies. For people who need money to buy a vehicle, purchase gold, expand a business, or meet personal expenses, NBFCs can be an important source of credit.
Unlike banks, NBFCs generally cannot accept demand deposits such as savings and current account deposits. However, they offer many services similar to those of banks, including personal loans, business loans, vehicle financing, gold loans, and housing finance. They also help people who may find it difficult to obtain loans through traditional banking channels.
India has several well-established NBFCs that operate across different financial segments. Some focus on consumer finance, while others specialise in commercial vehicles, gold loans, infrastructure projects, or housing finance. Their business models, customer groups, and financial performance differ significantly.
In this article, we will explore the top 10 NBFC companies in India in 2026, their major services, and their latest available financial performance, including revenue or income and net profit.
List of the Top 10 NBFC Companies in India
The following companies are selected based on their size, lending activities, market presence, and importance in India’s financial sector. This is a practical overview, not a strict ranking by one financial measure, because NBFCs operate in different business segments.
| Company | Main area of business |
| Bajaj Finance | Consumer and business finance |
| Power Finance Corporation (PFC) | Power and infrastructure financing |
| REC Limited | Rural electrification and power financing |
| Shriram Finance | Commercial vehicles and retail lending |
| Tata Capital | Personal, business, and housing loans |
| Cholamandalam Investment and Finance Company | Vehicle and business finance |
| Muthoot Finance | Gold loans |
| Mahindra Finance | Vehicle and rural finance |
| Aditya Birla Finance | Business and diversified lending |
| L&T Finance | Retail, rural, and business finance |
Bajaj Finance Limited
Image Courtesy: Bajaj Finance Limited (Official Website)
Bajaj Finance is one of India’s leading private-sector NBFCs. It is part of the Bajaj Finserv group and offers financial products to individuals, professionals, and businesses. Its large customer base, wide product range, and strong digital presence have helped it become a major name in consumer lending.
Main services
Bajaj Finance provides personal loans, consumer durable loans, business loans, loans against property, home loans, and financing for two-wheelers and other purchases. It also offers fixed deposits and selected investment-related services.
For example, a customer purchasing a refrigerator or laptop on instalments may use financing offered by Bajaj Finance. A small business owner may also approach the company for funds to purchase equipment or manage working capital.
Latest financial performance
According to the company’s FY2025–26 annual results, Bajaj Finance reported the following headline figures.
| Financial indicator | FY 2025–26 |
| Net total income | ₹53,324 crore |
| Profit after tax (PAT) | ₹20,689 crore |
| Assets under management (AUM) | ₹5,09,975 crore |
The company reported 22% growth in assets under management and 24% growth in profit after tax compared with the previous year, based on its published FY26 highlights. Its AUM represents the loans and other financial assets it manages, not its revenue.
Power Finance Corporation (PFC)
Image Courtesy: Power Finance Corporation (PFC) (Official Website)
| Company | Power Finance Corporation (PFC) |
| Industry Ranking | 1st among NBFCs in the 2025 Elets BFSI ranking |
| Reported Financial-Size Measure | ₹11,78,087 crore |
| Main Business | Power and infrastructure financing |
| Loan Tenure | Often long-term |
Power Finance Corporation is a government-owned NBFC that focuses mainly on financing India’s power sector. Unlike consumer-focused lenders, PFC primarily works with organisations involved in electricity generation, transmission, and distribution.
The company plays an important role in supporting power infrastructure. Electricity projects require significant investment, and funding from specialised financial institutions can help utilities and project developers build or improve their facilities.
Main services
PFC provides loans and financial assistance for power generation projects, transmission networks, distribution infrastructure, and certain renewable energy projects. It also offers financing and advisory support for eligible power-sector organisations.
For example, an electricity distribution company that needs to upgrade its network may seek financing to improve its infrastructure and reduce technical losses.
REC Limited
Image Courtesy: REC Limited (Official Website)
| Company | REC Limited |
| Industry Ranking | 2nd among NBFCs in the 2025 industry ranking |
| Reported Financial-Size Measure | ₹5,49,786 crore |
| Main Business | Power and infrastructure financing |
REC Limited, formerly known as Rural Electrification Corporation, is another major government-owned NBFC. It provides financing for electricity infrastructure and related projects across India.
REC was established to support rural electrification and has expanded into a wider range of power-sector financing activities. It now plays an important role in funding projects that support electricity generation, transmission, distribution, and renewable energy.
Main services
REC offers loans to power utilities, state electricity distribution companies, and eligible infrastructure project developers. It also finances certain renewable energy projects, including solar and wind power.
For example, a state electricity utility may require long-term funding to expand its distribution network or improve electricity supply in underserved areas. REC can help provide the financing needed for such projects.
Why is REC important?
REC supports projects that improve access to electricity and strengthen India’s energy infrastructure. It is also relevant to the expansion of renewable energy, which requires substantial investment in generation and transmission.
PFC and REC are often discussed together because both have an important role in financing India’s power sector. However, they are separate companies with their own financial statements and lending portfolios.
Shriram Finance Limited
Image Courtesy: Shriram Finance Limited (Official Website)
Shriram Finance is one of India’s major retail asset-financing NBFCs. It has a strong presence in commercial vehicle financing and also serves individuals, small businesses, and customers in rural and semi-urban areas.
The company was formed through the merger of Shriram Transport Finance Company, Shriram City Union Finance, and Shriram Capital entities in 2022. This helped bring several lending activities under one organisation.
Main services
Shriram Finance provides loans for commercial vehicles, passenger vehicles, two-wheelers, construction equipment, farm equipment, gold, and small businesses. It also offers personal loans and deposit products.
Its commercial vehicle business is particularly important. A truck operator may need financing to purchase a vehicle and earn income through transportation services. Shriram Finance helps such customers access funds through structured repayment plans.
Latest financial performance
The company’s FY2025–26 directors’ report provides the following standalone figures.
| Financial indicator | FY 2025–26 |
| Profit before tax | ₹13,292.26 crore |
| Profit after tax | ₹9,998.15 crore |
Shriram Finance reported a higher profit after tax than in FY2024–25, when standalone PAT was ₹9,761 crore. These are standalone figures and should not be directly compared with another company’s consolidated results without checking the reporting basis.
As of June 30, 2026, the company reported assets under management of approximately ₹3.14 lakh crore and a network of 3,225 branches.
Tata Capital Limited
Image Courtesy: Tata Capital Limited (Official Website)
| Company | Tata Capital Limited |
| Financial Year | FY 2023–24 |
| Total Income | Approximately ₹13,309 crore |
| Net Profit | Approximately ₹2,492.5 crore |
| Data Source | Dun & Bradstreet BFSI 500 report |
| Note | Historical FY24 figures; not FY26 results |
Tata Capital is a financial services company belonging to the Tata Group. It provides financing solutions to individuals, businesses, and companies across different industries. Its association with the Tata Group and its diversified product portfolio make it a well-known name in India’s financial sector.
Main services
Tata Capital offers personal loans, business loans, home loans, loans against property, vehicle finance, and financing for businesses and infrastructure-related needs. Its housing finance business also serves customers looking to purchase or construct homes.
For example, an individual planning to purchase a house may apply for a home loan, while a business owner may seek a loan to expand operations or purchase equipment.
Why is Tata Capital important?
Tata Capital serves multiple customer groups rather than relying on one type of loan. This diversification allows it to participate in retail lending, housing finance, and business financing.
For customers, the key consideration is whether the particular loan product suits their needs. Interest rates, eligibility, processing charges, repayment periods, and foreclosure conditions can vary across products.
Cholamandalam Investment and Finance Company Limited
Image Courtesy: Cholamandalam Investment and Finance Company (Official Website)
Cholamandalam Investment and Finance Company, commonly known as Chola Finance, is a major private-sector NBFC and part of the Murugappa Group. The company has a strong presence in vehicle financing and also provides loans to individuals and businesses.
It serves customers in cities as well as smaller towns, helping them finance vehicles, equipment, and other important purchases.
Main services
Its major products include commercial vehicle loans, used-vehicle loans, passenger vehicle finance, home equity loans, loans for small and medium-sized businesses, and financing for construction equipment.
For example, a small contractor who needs an additional vehicle for a construction project may approach Chola Finance for funding. A small business may also use a loan against property to raise money for expansion.
Latest financial performance
Chola Finance reported the following FY2025–26 figures in its directors’ report.
| Financial indicator | FY 2025–26 |
| Gross income | ₹31,444.84 crore |
| Profit before tax | ₹6,960.66 crore |
| Profit after tax | ₹5,219.59 crore |
Its FY2025–26 gross income increased from ₹26,054.76 crore in the previous year, while profit after tax increased from ₹4,258.53 crore.
The company also reported growth in its loan business, reflecting demand for vehicle finance and other lending products. Gross income is the figure reported in the directors’ report; it is not necessarily the same as revenue from operations under every reporting definition.
Why is Chola Finance important?
Chola Finance has built a strong position in asset-backed lending, where a vehicle or property may serve as security for a loan. Such financing supports customers who need money to acquire productive assets.
Its performance is influenced by loan demand, interest rates, operating expenses, and the company’s ability to collect repayments on time.
Muthoot Finance Limited
Image Courtesy: Muthoot Finance Limited (Official Website)
| Company | Muthoot Finance Limited |
| Financial Year | FY 2025–26 |
| Consolidated Total Income | ₹3,12,634.10 crore (as reported in the financial summary; unit requires verification) |
| Profitability | Reported to be strong in FY26 |
| Data Source | Arihant Capital and Muthoot Finance annual report |
Muthoot Finance is one of India’s best-known gold loan NBFCs. It specialises in lending money against gold jewellery, making it an important source of short-term credit for households, small traders, and business owners.
Gold loans are different from unsecured personal loans because the borrower pledges gold as security. The lender assesses the gold and offers a loan based on its eligible value and applicable lending rules.
Main services
Muthoot Finance’s core business is gold loans. It also has businesses and subsidiaries operating in areas such as housing finance, personal lending, and other financial services.
A customer may use a gold loan to pay an urgent medical bill, manage a temporary cash shortage, or meet a business expense. Since the loan is secured by gold, it may be available to some borrowers who do not have a conventional credit history.
However, borrowers must repay the loan according to the agreement. If they fail to do so, the lender may take steps to recover the outstanding amount, including selling the pledged gold after following applicable rules and procedures.
Why is Muthoot Finance important?
Muthoot Finance serves people who need funds quickly and can provide gold as collateral. Gold loans are often used for short-term financial needs, but they still carry interest costs and repayment obligations.
Customers should compare the loan-to-value ratio, interest rate, processing fees, repayment schedule, and consequences of default before pledging their jewellery.
Mahindra & Mahindra Financial Services Limited
Image Courtesy: Mahindra & Mahindra Financial Services Limited (Official Website)
Mahindra Finance is part of the Mahindra Group and has a strong presence in rural and semi-urban India. The company focuses on vehicle finance, rural lending, and financing for customers who may have limited access to traditional banking services.
Its rural reach is especially important because farming, transport, and small businesses often require financing to purchase vehicles and productive equipment.
Main services
Mahindra Finance provides loans for utility vehicles, cars, tractors, commercial vehicles, and other assets. It also offers selected personal and business financing products.
For example, a farmer may require a tractor to improve farm productivity, while a small transport operator may need a vehicle to expand a local business. Mahindra Finance provides financing options for such purchases, subject to eligibility.
Latest financial performance
The company’s published FY2025–26 summary reports the following financial indicators.
| Financial indicator | FY 2025–26 |
| Total income | ₹16,075 crore |
| Profit before tax | ₹3,147 crore |
| Profit after tax | ₹2,345 crore |
These figures provide an indication of the company’s earnings and scale. Total income includes the income reported under its financial reporting framework and should not be confused with the amount of loans disbursed during the year.
Why is Mahindra Finance important?
Mahindra Finance combines vehicle financing with a strong rural distribution network. Its business is connected to demand for farm equipment, transport vehicles, and other assets used by households and small businesses.
Its lending performance can be affected by rural incomes, agricultural conditions, vehicle demand, and borrowers’ repayment capacity. These factors make credit assessment and collection practices particularly important.
Aditya Birla Finance Limited
Image Courtesy: Aditya Birla Finance Limited (Official Website)
| Company | Aditya Birla Finance Limited |
| Business Category | Private-sector diversified NBFC |
| Assets Under Management (AUM) | ₹1,19,437 crore |
| Reporting Date | 31-Dec-24 |
| Data Source | Aditya Birla Capital |
| Important Note | The AUM figure is historical and should not be treated as FY26 revenue or current assets. |
Aditya Birla Finance is part of the Aditya Birla Capital group and is a diversified NBFC. It focuses on lending to individuals, professionals, small businesses, and large companies.
Unlike lenders that concentrate mainly on gold or vehicle loans, Aditya Birla Finance operates across several lending segments. This allows it to serve customers with different borrowing requirements.
Main services
The company’s lending activities include personal loans, business loans, loans against property, corporate financing, and other secured and unsecured credit products. It also offers financing solutions to businesses that need funds for working capital or expansion.
For example, a company may require additional working capital to purchase inventory before receiving payments from customers. A suitable loan can help manage that temporary gap, provided the borrowing cost is affordable.
L&T Finance Limited
Image Courtesy: L&T Finance Limited (Official Website)
L&T Finance is a major NBFC associated with the Larsen & Toubro group. It has developed a strong retail lending business, with activities covering rural finance, housing finance, and loans for individuals and businesses.
The company has increasingly focused on retail lending and technology-based processes to improve customer service, loan assessment, and collections.
Main services
L&T Finance provides rural business finance, farm-related loans, two-wheeler loans, housing finance, and other retail credit products. It also serves customers through digital channels and physical distribution networks.
For example, a customer purchasing a two-wheeler for daily commuting may seek financing, while a rural household or small business may require credit for a productive activity.
Latest financial performance
According to its FY2025–26 results announcement, L&T Finance reported consolidated profit after tax of ₹3,003 crore for FY26, before the effect of the labour-code provision considered in the third quarter. The company reported year-on-year growth of 14% on that basis. Its consolidated loan book stood at ₹1,21,728 crore at the end of the financial year.
| Financial indicator | FY 2025–26 |
| Consolidated profit after tax | ₹3,003 crore |
| Consolidated loan book at March 31, 2026 | ₹1,21,728 crore |
| Retail loan book at March 31, 2026 | ₹1,19,508 crore |
The profit figure is presented on the company’s stated basis, so it should not be treated as identical to an adjusted or reported PAT figure that includes all exceptional expenses.
Comparison of the Top NBFC Companies in India
The following table brings together the main financial figures discussed above. The figures are not perfectly comparable because they cover different reporting bases and, in some cases, different financial years.
| Company | Latest clearly stated income figure | Profit after tax |
| Bajaj Finance | ₹53,324 crore, FY26 net total income | ₹20,689 crore, FY26 |
| Power Finance Corporation | Refer to latest audited annual report | Not stated here |
| REC Limited | Refer to latest audited annual report | Not stated here |
| Shriram Finance | Refer to FY26 audited income statement | ₹9,998.15 crore, FY26 standalone |
| Tata Capital | ₹13,309 crore, FY24 total income | ₹2,492.5 crore, FY24 |
| Chola Finance | ₹31,444.84 crore, FY26 gross income | ₹5,219.59 crore, FY26 |
| Muthoot Finance | Verify original audited statement and units | Verify audited FY26 statement |
| Mahindra Finance | ₹16,075 crore, FY26 total income | ₹2,345 crore, FY26 |
| Aditya Birla Finance | Refer to latest audited subsidiary accounts | Not stated here |
| L&T Finance | Refer to latest audited income statement | ₹3,003 crore, FY26 on the company’s specified basis |
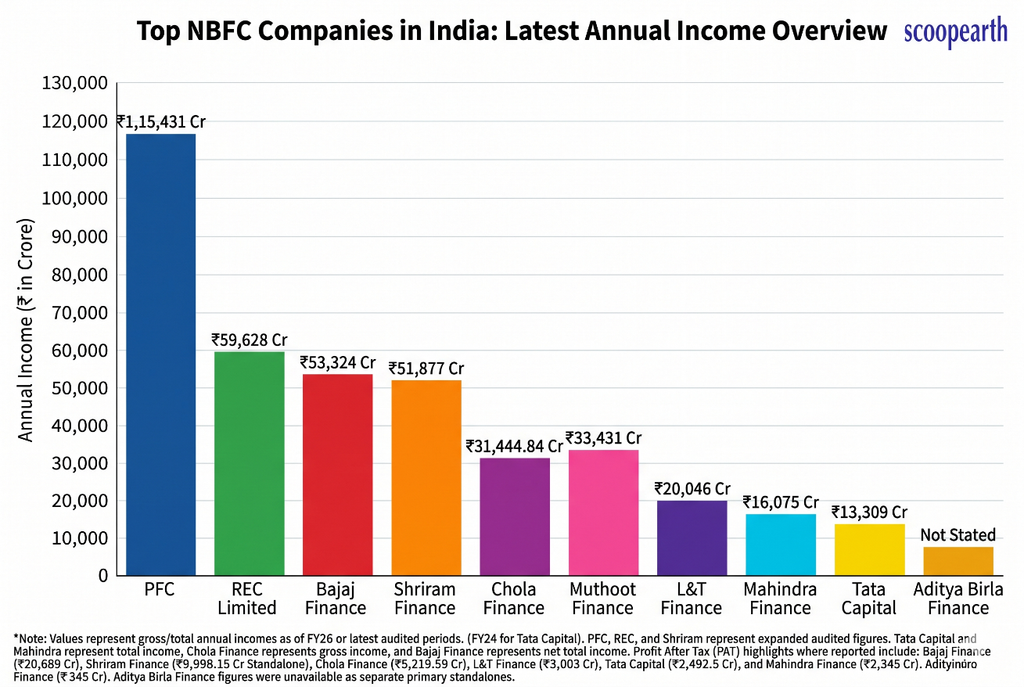
This table intentionally leaves certain values unreported instead of presenting unverified figures as facts. When comparing companies, always check whether the data is standalone or consolidated and whether the income measure is total income, gross income, or net total income.
Conclusion
NBFCs are an important part of India’s financial system. They help individuals, small businesses, farmers, and large organisations access financing for everyday needs, asset purchases, and long-term projects.
Among the companies discussed, Bajaj Finance is a major player in consumer and business lending, PFC and REC focus on power infrastructure, Shriram Finance and Mahindra Finance have strong vehicle and rural financing businesses, and Muthoot Finance specialises in gold loans. Tata Capital, Chola Finance, Aditya Birla Finance, and L&T Finance offer diversified lending solutions across several customer segments.
Their financial performance also shows why it is important to look beyond company size. Revenue or income, net profit, assets under management, loan growth, borrowing costs, and loan quality all help explain how an NBFC operates.
For customers, the best NBFC is not necessarily the largest one. It is the lender that offers an appropriate product, clear terms, reasonable borrowing costs, and a repayment schedule that fits the customer’s financial situation. For investors and business readers, comparing audited financial statements and understanding each company’s lending focus provide a more reliable picture of its position in India’s financial sector.
Frequently Asked Questions (FAQs)
What is an NBFC?
An NBFC is a Non-Banking Financial Company that provides loans and other financial services.
Which are the top NBFC companies in India?
Bajaj Finance, PFC, REC, Shriram Finance, and Tata Capital are among India’s leading NBFCs.
What is the full form of NBFC?
NBFC stands for Non-Banking Financial Company.
How are NBFCs different from banks?
NBFCs provide many lending services like banks but generally cannot accept demand deposits.
Which NBFC is best for personal loans in India?
Bajaj Finance, Tata Capital, and other established lenders offer personal loans, depending on eligibility.
Which NBFC is famous for gold loans?
Muthoot Finance is one of India’s best-known gold loan providers.
Which NBFC focuses on power sector financing?
Power Finance Corporation (PFC) and REC Limited mainly finance power and infrastructure projects.
Which NBFC provides commercial vehicle loans?
Shriram Finance and Mahindra Finance are major providers of commercial vehicle financing.
Are NBFCs regulated in India?
Yes, NBFCs are regulated by the Reserve Bank of India (RBI), subject to applicable regulations.
Can NBFCs provide home loans?
Yes, eligible NBFCs and housing finance companies provide loans for purchasing or constructing homes.
Do NBFCs charge interest on loans?
Yes, NBFCs charge interest and may also apply processing fees and other charges.
What does AUM mean in an NBFC?
AUM stands for Assets Under Management and generally refers to the loans and other financial assets managed by the company.
Are NBFCs safe for borrowing money?
Borrowers should choose a regulated lender and carefully review its interest rates, fees, and repayment terms.
How do NBFCs earn money?
NBFCs mainly earn money through interest on loans and fees for financial services.
What should customers check before choosing an NBFC?
Customers should compare interest rates, processing fees, repayment terms, lender credibility, and penalties before borrowing.